Pick a fixed rate if you value repayment certainty over the lowest possible starting cost, and a floating rate if you can absorb rate swings for a chance at cheaper early payments. A fixed package holds your rate for a lock-in of typically 2 to 5 years, while a floating loan moves with SORA. Eligible HDB buyers also have the HDB concessionary loan.
TL;DR:
- Compare each offer’s Effective Interest Rate, not its headline rate, because calculation methods and features such as offset accounts can change the actual cost.
- A SORA package combines a bank spread with a benchmark averaged over one, three, or six months; shorter averages react sooner, while longer ones lag.
- Before choosing floating, calculate payments after a 1 to 2 percentage point SORA rise; if that increase strains your budget, favor repayment certainty.
- Fixed terms typically last two to five years, but early refinancing or prepayment can trigger break fees, so compare exit costs before signing.
- Eligible HDB buyers can consider the concessionary loan, pegged 0.1% above the CPF Ordinary Account rate and adjusted only when CPF rates change.
Table of Contents
- How fixed and floating home loans work in Singapore
- How SORA changes your floating repayments
- How to choose between fixed and floating
- Lock-in periods, break fees and refinancing timing
- Practical steps to cushion repayments and manage rate risk
- What Singapore data and regulators say
- Matching your loan to your holding plan
- One Marina Gardens: a home that fits your financial plan
- FAQ
- Sources
How fixed and floating home loans work in Singapore
A fixed-rate loan keeps your interest rate constant for a set lock-in period, so your monthly instalment does not change during that window. In Singapore, banks commonly offer fixed terms of two to five years, after which you must choose a new package. What you are buying is stability: you know the number before the rate environment changes.
A floating-rate loan works differently. Its rate is built from two pieces: a benchmark, most often SORA, plus a bank spread. Add them together and you get the all-in rate. The package rate combines a benchmark and a bank spread. The benchmark moves with market conditions. When market rates fall, your payments can fall with them. When they rise, so do your repayments.
Headline rates alone can mislead you. Two packages with the same advertised rate can cost different amounts depending on how interest is calculated, whether on a flat-rate basis or a monthly rest basis, and on features like offset accounts or prepayment flexibility. That is why MoneySense tells borrowers to compare the Effective Interest Rate (EIR), which reflects how interest is actually charged, rather than the headline figure.
Here is the trade-off in plain terms:
- Fixed: Predictable instalments during the lock-in, but the starting rate is generally priced higher than floating because the bank is covering rate-volatility risk.
- Floating: Payments follow market rates, which can help in a falling market and hurt in a rising one, with no promise of what next year looks like.
- Either way: The true cost depends on EIR, not the advertised rate.
When you compare offers, run three quick checks. First, note the advertised rate. Second, ask for the EIR on the same package. Third, split a floating offer into its benchmark and its spread, so you can see how much of the rate is fixed and how much will move. A package that looks cheap on the brochure can look ordinary once you see the EIR and the spread side by side.
One more point on pricing. Banks charge more for certainty, and that premium is the cost of the lock. A fixed rate is not a bargain or a trap on its own. It is a price you pay for knowing your instalment. Whether that price is worth it depends on how much a surprise would hurt your monthly budget.
How SORA changes your floating repayments
SORA, the Singapore Overnight Rate Average, has replaced SOR and SIBOR as the key Singapore benchmark. If you read older loan guides, you will see those legacy names, but a floating package today is built on SORA. MoneySense confirms that SORA replaced SOR and SIBOR as the benchmark that matters for new borrowers and for those switching.
What makes SORA different is how banks use it. Many SORA-based packages reference a compounded average over one, three or six months rather than a single daily reading. That averaging tends to smooth short-term spikes, so one jumpy week in the money market does not hit your instalment the next day. It does not remove rate risk, because a sustained rise still feeds through, but it softens the sharp edges.
Here is how the pieces fit together:
- The benchmark: Compounded 1-, 3- or 6-month SORA, which reflects market conditions averaged over that window.
- The spread: The bank's margin on top, usually fixed for the package.
- The all-in rate: Benchmark plus spread, which is what your monthly payment is actually based on.
This matters when you compare a SORA package with an older-style one. Legacy benchmarks may behave differently, so borrowers switching packages should check how the new rate is calculated. If you are moving from a SOR or SIBOR package, check which compounding period the new package uses, because shorter and longer averages can respond differently to market changes.
For borrowers deciding between floating options, the compounding period is worth asking about directly. A shorter window follows the market more closely, so you feel changes sooner. A longer window lags, which can protect you in a sudden spike but also delays the benefit when rates fall. Neither is better in every market. It depends on whether you would rather feel changes early or late.
For a deeper look at how the old and new benchmarks differ and what to ask a lender, see our guide on SORA vs SIBOR for Singapore borrowers.
How to choose between fixed and floating
Start with what you cannot compromise on. If a higher instalment would strain your household budget, certainty should carry more weight than a slightly lower starting rate. If you have room in your cash flow and a long horizon, you may accept variability for a chance at lower cost.
Five criteria do most of the work:
- Repayment certainty versus expected cost. Fixed buys predictability. Floating may cost less at the start but offers no guarantee.
- Holding horizon. How long you plan to keep the loan before selling or refinancing.
- Risk tolerance. How much of a payment swing you can absorb without stress.
- Refinancing plans. Whether you intend to switch packages when a lock-in ends.
- Flexibility features. Offset accounts or prepayment options that change the real cost.
Then work through the decision in order:
- Set your time horizon. Decide whether you expect to hold the property and loan for a short stretch or many years. A fixed term of two to five years suits a buyer who expects to reassess in that window.
- Run an EIR comparison under stress. Ask each bank for the EIR and calculate monthly payments for each package, then test what happens if rates rise.
- Check lock-in and break-fee clauses. Know what it costs to leave early before you sign.
- Confirm refinance options at lock-in end. Ask what package you would roll into and how the bank handles the switch.
Pro Tip: Ask each bank for both the advertised rate and the EIR, then simulate a 1 to 2 percentage point rise in SORA to see whether the instalment still fits your budget.
The stress test is the step most borrowers skip, and it is the one that tells you the most. A floating loan can look cheaper on day one and feel very different after a sustained rise. Running the numbers under a higher-rate scenario shows you whether you would be comfortable or squeezed. If a modest rise leaves you stretched, that points toward fixed.
Local data helps put your choice in context. MAS reported that, as of Q2 2022, about 20% of HDB flat loans and about 37% of private residential loans were on floating packages, with the rest on fixed or board-rate-based packages. Borrowers are clearly split, which is a reminder that neither choice is the single right answer. Your own finances and plans decide it.
Loan tenure also shapes the decision. Over a long tenure, a fixed lock-in covers only the first slice of the loan, so you will face a rate decision again when it ends. Over a shorter tenure, a larger share of the loan sits inside the fixed period. Either way, plan for the day the lock-in expires rather than treating the fixed rate as permanent.

Do not forget the HDB concessionary loan if you qualify. It is a distinct alternative to bank packages, covered in our post on home loan options in Singapore, and its rate mechanics work differently from a bank's.
Lock-in periods, break fees and refinancing timing
The end of a fixed period is the moment that matters most. Banks in Singapore typically expect you to choose a new package when your lock-in expires. If you do nothing, the loan often reverts to a standard variable rate, which is rarely the best deal on offer. That makes the expiry date the natural time to refinance or renegotiate.
Plan ahead rather than react. A common approach is to start comparing offers a few months before the lock-in ends, so you have time to get quotes, check fees and decide without pressure. Mark the date in your calendar when you sign, and treat it as a decision point, not an afterthought.
Leaving a fixed package early can cost you. MoneySense notes that fixed-rate loans often restrict flexibility, with break fees on refinancing or prepaying within the lock-in, sometimes calculated on the interest-rate differential. In plain terms, the bank charges you for the interest it expected to earn at the locked rate that it will no longer receive.
This is why repricing and refinancing are different moves. Repricing means switching to a new package with your current bank, while refinancing means moving the loan to another bank. Each can carry its own costs and timing, so compare both at the point you are free to act, and check what each would cost before assuming either is cheaper.
Before you sign any package, put these questions to your bank:
- How is the break fee calculated, and what would it be on a sample scenario?
- What notice period applies if I want to change or repay?
- What happens after the lock-in ends, and what rate would I move to?
- Are there limits on partial prepayment during the fixed period?
- Does a legal or valuation fee apply when I switch?
Write the answers down. A verbal assurance is easy to forget, and the written terms are what bind you. Asking for a worked example of a break fee, with real numbers for your loan size, turns an abstract clause into something you can weigh.
Practical steps to cushion repayments and manage rate risk
You cannot control rates, but you can control how exposed you are when they move. Start with a cash buffer, then test your budget against a tougher scenario than today's rates.
MAS applies a medium-term interest-rate floor for property loan assessments. Under the TDSR and MSR frameworks, the medium-term floor is set at 4% per annum. Using a comparable stress level when you plan your own budget is a sensible habit, because it shows whether your instalment would still be manageable if rates were well above today's.
Practical measures to put in place:
- Build a buffer. Hold enough liquid cash to cover several months of instalments, so a rate rise does not force a scramble.
- Use offset or prepayment features. Where your package allows, partial prepayment and offset accounts can reduce the interest you pay over time.
- Consider a shorter tenure. Faster repayment cuts the total interest, though it raises the monthly figure, so check it fits your budget.
- Keep an emergency repayment plan. Decide in advance what you would cut or draw on if payments rose.
Pro Tip: Before you meet a mortgage specialist, bring your EIR comparisons and a realistic forecast of your income, so the advice is built on your actual numbers rather than averages.
Know when to ask for help. If your numbers are close, or your income is uncertain, a conversation with a mortgage specialist can save you from a costly mismatch. The more prepared you arrive, the more useful the discussion will be.
What Singapore data and regulators say
The local evidence points the same way: borrowers are divided, and fixed pricing reflects the cost of certainty. MAS data shows a real split between fixed and floating packages across property types, and MAS has explained that banks price fixed-rate loans to cover interest-rate volatility risk, which is why fixed introductory rates are generally higher than floating ones.
For eligible HDB buyers, the concessionary loan offers a reference point with different mechanics.
HDB's concessionary loan is pegged 0.1% above the CPF Ordinary Account interest rate, so it moves only when CPF rates change. That makes it a steadier alternative to a market-linked bank package for those who qualify.
Matching your loan to your holding plan
Our view is simple: let your holding horizon drive the loan, not the other way around. If you expect to sell or refinance within a few years, a fixed package whose lock-in matches that window gives you certainty for exactly as long as you need it. If you plan to hold for the long run and are comfortable with market cycles, a floating package may lower your initial cost, provided you have stress-tested the downside.
The detail buyers underrate is how much small differences compound. A slightly higher EIR or an unexpected break fee, repeated over a long tenure, can outweigh the headline saving that attracted you in the first place. Compare the full cost, not the teaser rate, and read the early-exit terms before you fall for a number.
For condo buyers, the loan and the purchase should be planned together. Cash flow during construction, the downpayment and the repayment schedule all interact, so a plan that works on paper at one rate can strain at another. For more on the numbers, see our condo downpayment guide and our explanation of the progressive payment scheme.
If you are a foreign buyer, remember that tax and relocation questions sit alongside the loan. A guide to moving to Singapore from the US can help with that wider picture.
— Velisa
One Marina Gardens: a home that fits your financial plan
Once you know how you will finance a purchase, the next question is which home suits your plan. At One Marina Gardens, we offer a range of unit types in District 01:
- 2 Bedroom
- 3 Bedroom
- 3BR Premium
- 4BR Premium
Our development sits near Marina South MRT, with sky terraces, a lap pool and a childcare center on site. Those features matter for long-term holding decisions, because a home you want to keep is easier to finance with confidence.
Financing strategy matters for a prime condo because your downpayment, your TDSR planning and the timing of any resale all shape which loan makes sense.
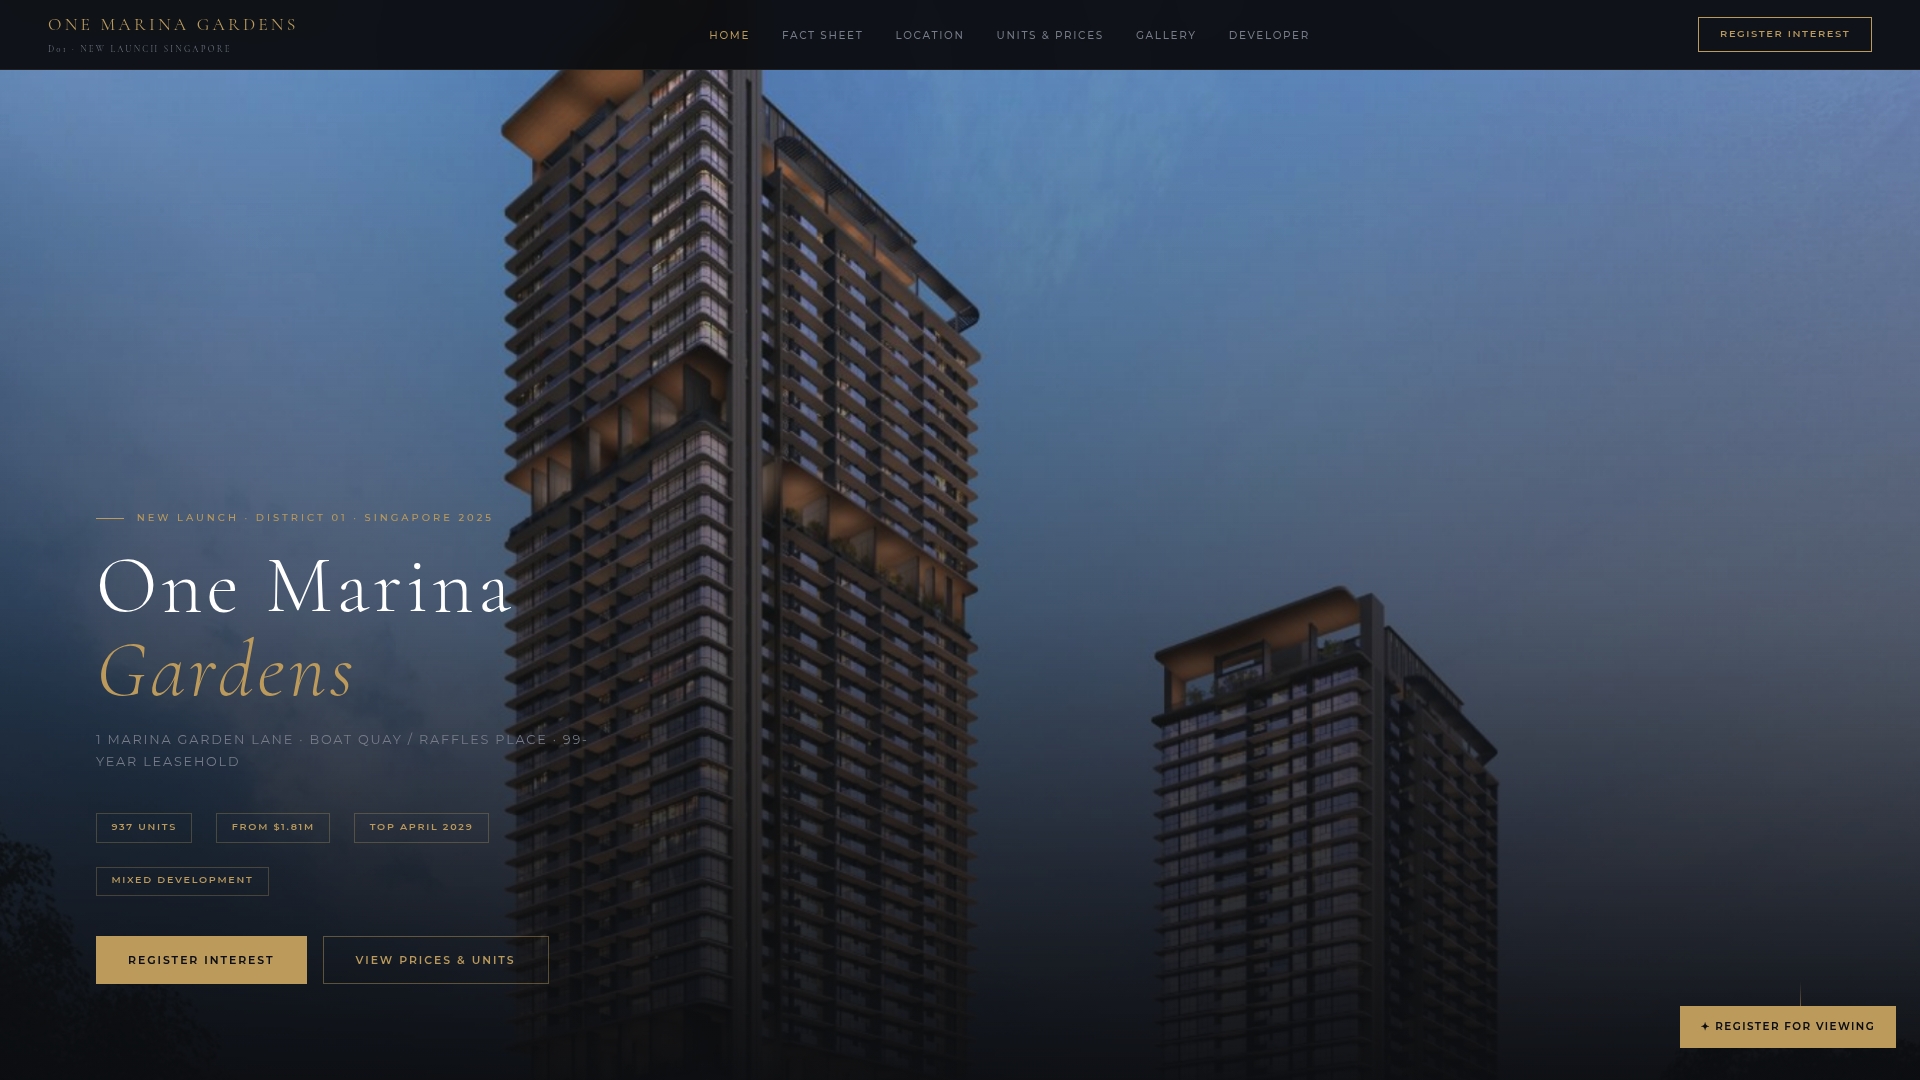
Browse our unit types and pricing, and book a showflat appointment.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
Which loan is better, fixed or floating?
Neither is better for everyone. Fixed suits borrowers who want stable instalments during the lock-in, while floating suits those who can handle rate swings for a chance at lower early costs. MAS notes that banks price fixed loans higher to cover rate-volatility risk.
Should I go for a fixed or floating home loan?
Decide based on your budget tolerance and holding plan. If a payment rise would strain you, lean fixed. If you have room in your cash flow and a long horizon, floating can make sense, ideally after stress-testing with a higher SORA.
How do I know my home loan is fixed or floating?
Check your letter of offer or loan statement for the package type and rate basis. A floating loan will show a benchmark such as SORA plus a spread, while a fixed loan states a rate and a lock-in period. Your bank can confirm if the wording is unclear.
Can I change my loan from fixed to floating?
Yes, but switching during a lock-in may trigger a break fee, sometimes calculated on the interest-rate differential. The cleanest time to switch is when your fixed period ends, so check the cost and your options with your bank first.